
How to Read a SaaS P&L From Revenue to Adjusted EBITDA
A SaaS P&L has rules down to EBITDA and none after it, so read the add-backs first: one Blackbaud quarter scores 41 on the Rule of 40, or 24 on GAAP margin.
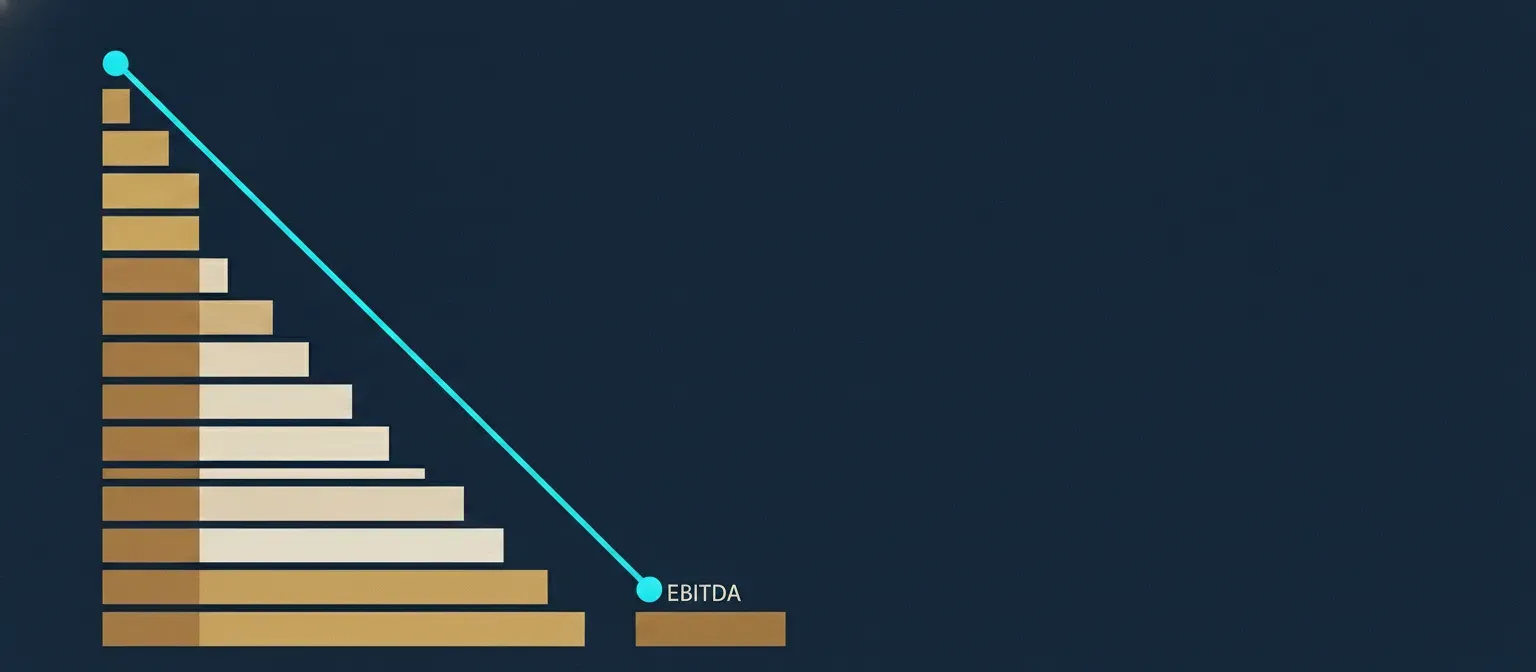
A SaaS P&L runs from revenue through cost of revenue and three operating lines to operating income; EBITDA then adds interest, taxes, depreciation and amortization back to net income. EBITDA is the last line with a regulator’s definition. After it, each company picks its own add-backs, led by stock-based compensation, so read the reconciliation before the margin.
The add-backs can decide the verdict. Blackbaud, a listed software company, reported a Rule of 40 score of 41.0% for the second quarter of 2026, defined as “non-GAAP organic revenue growth plus non-GAAP adjusted EBITDA margin” (Blackbaud, 2026). On the same quarter’s EBITDA margin the score is 31.8, and on its GAAP operating margin it is 24.3 (our arithmetic). The 16.7 points between the first and the last are add-backs, and a board can check them once it knows where the rules stop.
Most lines of a SaaS P&L are conventions that GAAP leaves open
Regulation S-X, the SEC’s rulebook for financial statements, lists the captions a listed company’s income statement should carry, from net sales and costs applicable to sales down to earnings per share. None of them is gross profit, research and development or EBITDA (17 CFR 210.5-03). The familiar SaaS P&L layout is a convention, and so is the content of each line. SaaS Capital, a lender to software companies, notes that “GAAP does not clearly define what should be included in a SaaS company’s Cost of Sales”. It calls it “now established best practice to include the customer support and customer success department in Cost of Goods Sold” (SaaS Capital, 2024).
That one choice can move gross margin by several points. Support and success cost a median 9% of ARR in SaaS Capital’s 2026 survey, which drew on over 1,000 private companies (SaaS Capital, 2026). A company that books the team under sales and marketing can therefore show a gross margin roughly 9 points above an otherwise identical company that follows the lender’s convention. Both layouts are legal. Below gross profit the same freedom applies to every operating line of a SaaS P&L, until the statement reaches EBITDA.
EBITDA has a definition, and adjusted EBITDA has a reconciliation
The rules that do exist sit at the bottom of the statement, and they arrived because of abuse. On 25 October 1999, Trump Hotels & Casino Resorts reported quarterly net income of $14.0 million, or $0.63 a share, “before a one-time Trump World’s Fair charge” of $81.4 million, ahead of the First Call estimate of $0.54. The release did not say that the stated net income included an undisclosed one-time gain of $17.2 million. Without it, the quarter would have missed. In January 2002 the SEC called its order “the first Commission enforcement action addressing the abuse of pro forma earnings figures” (SEC, 2002).
Section 401(b) of the Sarbanes-Oxley Act, signed on 30 July 2002, told the SEC to write rules for such figures, which it named non-GAAP financial measures. Regulation G took effect on 28 March 2003. A listed company that publishes such a measure must show the most directly comparable GAAP measure and a quantitative reconciliation (SEC, 2003; 17 CFR 244.100). EBITDA kept one special status: it may leave out cash-settled charges even when used as a liquidity measure, “because of their wide and recognized existing use”, but “registrants must reconcile these measures to their most directly comparable GAAP financial measure.”
The SEC staff later pinned the word down. Earnings, in EBITDA, “means net income as presented in the statement of operations under GAAP”; a measure built any other way needs a different title, such as Adjusted EBITDA (Question 103.01). The staff also warns that a measure which “excludes normal, recurring, cash operating expenses necessary to operate a registrant’s business” could mislead (Question 100.01; SEC staff interpretations). Within those limits, adjusted EBITDA is what a listed company says it is, provided it prints the bridge. A private company’s board pack carries no such duty.
Stock-based compensation is the largest add-back, and it is a cost
In software the largest add-back is usually stock-based compensation. The table below compares three listed companies.
Three software companies, one quarter each: the margin they headline and the margin GAAP reports
| Palantir | Snowflake | Blackbaud | |
|---|---|---|---|
| Quarter | Q2 2026, to 30 June | Q2 fiscal 2027, to 31 July 2026 | Q2 2026, to 30 June |
| Revenue growth, year on year | 93% | 35% | 3.0% |
| GAAP operating margin | 47.1% | −17.0% | 21.3% |
| Stock-based compensation, % of revenue | 13.7% | 29.5% | 7.8% |
| Headline margin, company’s own measure | 61.7%, adjusted operating margin | 15.3%, non-GAAP operating margin | 38.0%, adjusted EBITDA margin |
| Headline minus GAAP operating margin, points | 14.6 | 32.3 | 16.7 |
| Rule of 40 on the headline margin | 155 (reported) | 50.3 | 41.0 (reported) |
| Rule of 40 on GAAP operating margin | 140 | 18.0 | 24.3 |
Source: Palantir and Blackbaud earnings releases (Form 8-K, Exhibit 99.1); Snowflake earnings release, 2 September 2026. Snowflake’s figure is its “stock-based compensation-related charges”, which include payroll taxes. Margins, differences and the unreported Rule of 40 scores are computed from the releases.
The distance from GAAP to the headline runs from 14.6 to 32.3 points: points added back = headline adjusted margin − GAAP operating margin. Stock compensation supplies most of it at Palantir and Snowflake; at Blackbaud, depreciation and amortization add 7.5 points and stock compensation 7.8. Snowflake’s GAAP operating loss of $263.0 million becomes non-GAAP operating income of $237.0 million, a $500 million swing, of which $456.4 million is stock compensation charges (Snowflake, 2026). Its 10-Q says stock-based compensation “represented 34% of our revenue for fiscal 2026”, and $3.8 billion of granted awards remain to be expensed (Snowflake 10-Q, 2026).
No cash leaves for the stock, but the cost is real. Warren Buffett’s 1992 letter to Berkshire Hathaway shareholders asked: “If options aren’t a form of compensation, what are they? If compensation isn’t an expense, what is it? And, if expenses shouldn’t go into the calculation of earnings, where in the world should they go?” (Buffett, 1992). Berkshire, he added, had “far more confidence in our ability to determine an appropriate price to pay for an option than we have in our ability to determine the proper depreciation rate for our corporate jet”. Today the expense sits on the face of the GAAP statement: Palantir’s footnote spreads its $265.2 million across cost of revenue, sales and marketing, R&D and G&A (Palantir, 2026).
Part of the add-back is cash. Palantir also adds back $17.3 million of employer payroll taxes on stock compensation, excluded “as it is difficult to predict and outside of Palantir’s control”. Unlike the stock, the tax is paid in cash, and Palantir’s own free cash flow bridge shows $18.7 million of it in the quarter. The choice of margin also changes comparisons between companies: set Snowflake’s 15.3% against Blackbaud’s 38.0% and the gap is 22.7 points, while on GAAP operating margin it is 38.3 points.
Capitalized development never reaches EBITDA
Under ASC 350-40, software development that meets its criteria is capitalized: the cost goes to the balance sheet and returns as amortization over the software’s life. EBITDA adds that amortization back, and the original spending appears only in investing cash flows, so development capitalized this way never reaches EBITDA at all. Blackbaud’s second-quarter bridge adds back $12.8 million of amortization of software development costs, 4.4% of revenue, and in the first half it capitalized $26.1 million, 4.6% of revenue. At that rate, comparing a capitalizing company’s EBITDA with an expensing peer’s would credit the first with 4 to 5 points of margin that its cash flow does not show. SaaS Capital’s advice to private companies is blunt: “Expense your software development costs, don’t capitalize them” (SaaS Capital, 2024).
Which earnings number predicts better, adjusted or GAAP?
The best case for adjusted figures is empirical. Nilabhra Bhattacharya, Ervin Black, Theodore Christensen and Chad Larson studied 1,149 pro forma press releases (Bhattacharya et al., 2003). Judged by share-price reactions and analysts’ forecast revisions, “pro forma earnings are more informative and more permanent than GAAP operating earnings”. Palantir makes the managerial case: it excludes stock compensation, “which is a non-cash expense”, to present results “in the same manner as our management team”.
For items that do not recur, such as restructuring, acquisition costs or an impairment, the pro forma figures do help a reader forecast, which is what the 2003 study measured. Stock compensation recurs every quarter by design. In a study published the same year, Jeffrey Doyle, Russell Lundholm and Mark Soliman examined the excluded items themselves. “Higher levels of exclusions lead to predictably lower future cash flows”, they found, and investors did not fully price that at the announcement (Doyle et al., 2003). Both studies cover listed companies’ releases from before Regulation G, so they say more about the habit than about any one board pack. Neither tests a private SaaS company.
GAAP and the SEC fix the recipes down to EBITDA. Beyond that line the company writes its own. The SEC staff calls an unexplained change in that recipe between periods potentially misleading (Question 100.02). In software the two largest ingredients, stock compensation and capitalized development, are costs that owners pay in shares or in cash the margin never shows. At Snowflake, the choice of margin takes a Rule of 40 score from 50.3 to 18.0, well under the 40 the rule asks for. On Blackbaud’s second quarter the recipe is worth 16.7 points: a Rule of 40 score of 41.0 on the company’s own measure, and 24.3 on its GAAP operating margin.
Sources and notes
- Bhattacharya, N., Black, E. L., Christensen, T. E. and Larson, C. R. (2003). Assessing the relative informativeness and permanence of pro forma earnings and GAAP operating earnings. Journal of Accounting and Economics 36, 285–319.
- Blackbaud, Inc. (2026). Second-quarter 2026 results, Form 8-K Exhibit 99.1.
- Buffett, W. E. (1992). Chairman’s letter to the shareholders of Berkshire Hathaway Inc. for 1992, dated 1 March 1993.
- Doyle, J. T., Lundholm, R. J. and Soliman, M. T. (2003). The predictive value of expenses excluded from pro forma earnings. Review of Accounting Studies 8, 145–174.
- Palantir Technologies Inc. (2026). Second-quarter 2026 results, Form 8-K Exhibit 99.1.
- SaaS Capital (2024). What Should a SaaS Income Statement Look Like? (2026). 2026 Spending Benchmarks for Private B2B SaaS Companies.
- SEC (2002). Press Release 2002-6, SEC Brings First Pro Forma Financial Reporting Case.
- SEC (2003). Release Nos. 33-8176 and 34-47226, Conditions for Use of Non-GAAP Financial Measures, 68 FR 4820.
- SEC, Division of Corporation Finance. Non-GAAP Financial Measures: Compliance and Disclosure Interpretations, Questions 100.01, 100.02 and 103.01.
- SEC. Regulation G, 17 CFR Part 244; Regulation S-X Rule 5-03, 17 CFR 210.5-03.
- Snowflake Inc. (2026). Second-quarter fiscal 2027 results; Form 10-Q for the quarter ended 31 July 2026.
Company figures come from the earnings releases and filings listed, the rules from the SEC’s own releases and staff interpretations, and the private-company median from SaaS Capital’s survey. Margins, differences and scores with no source beside them are worked out from the companies’ reported figures, and the two academic papers are cited for the findings their abstracts state.
More in SaaS Metrics & Unit Economics
Bookings vs Billings vs Revenue, Linked by Two Balances
Bookings vs billings vs revenue: signed, invoiced, earned. Only revenue has a rulebook; count bookings as ASC 606 counts RPO, by the noncancellable term.
Burn Rate Counts Months, and the Burn Multiple Prices ARR
Burn rate is the cash a company loses each month: gross burn counts payments, net burn subtracts collections. The burn multiple prices the ARR it buys.